Cashew—Expense Budget Tracker
- 4.7
- Rating
- 500.00K
- Installs
- Free
- Price
 Analysis by App-foxy
I found Cashew—Expense Budget Tracker most useful when I treated it less like a financial dashboard and more like a quiet daily check-in. It is a finance app from Dapper App Developer, built around recording spending and keeping an eye on a personal budget. That sounds simple, but simplicity matters when money management already feels tiring. I could open it, enter a purchase, and return to what I was doing without feeling as if I had started a bookkeeping project.
My overall impression is that Cashew suits people who want a focused expense tracker rather than a full banking command center. It is free to install, available to an Everyone audience, and its current version is 6.6.11. The app has reached over 500 thousand installs and holds a 4.7 average from roughly 27 thousand ratings, which suggests that its straightforward approach connects with many users. I would still recommend trying it with your own routine before committing to a detailed financial system, because the best tracker is the one you can comfortably use every day.
How Cashew feels to use when readability and navigation matter
The strongest part of the experience is the direct relationship between an action and its result. When I wanted to record an expense, I did not have to think about complicated accounting language. The app’s purpose stays visible: track what I spend, understand where it goes, and compare that behavior with the budget I set for myself. For someone who becomes overwhelmed by finance software filled with charts, accounts, and business terminology, this narrower focus can make the first session much less intimidating.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



I also think the app works well for people who prefer predictable routines. A useful habit is to enter a purchase immediately after paying, then look back at the day or week when deciding whether another expense fits. Cashew becomes easier to understand when used in this repeated sequence rather than as a place to reconstruct an entire month from memory. That is an important distinction: the app can support awareness, but it cannot make forgotten entries accurate.
Readability is not only about large text or visual contrast. It is also about whether the screen asks the user to interpret too much at once. Cashew’s expense-tracking purpose gives it an advantage here. A person who wants a quick answer to “how much have I spent?” is likely to find the focused layout easier to approach than a traditional spreadsheet. On the other hand, anyone who expects a highly detailed financial analysis may find the experience less satisfying because the simplicity that helps beginners can feel restrictive to advanced planners.
For a new user, I would begin with a small, realistic setup rather than trying to represent every financial detail immediately. Start with the expenses that most often surprise you, such as food away from home, transport, or small online purchases. After several days, adjust the categories or budget choices according to what you actually need. This method reduces the mental load and makes the app’s feedback more meaningful than an ambitious setup that becomes difficult to maintain.
A practical routine for people who dislike financial admin
My preferred workflow is to make one short entry at the moment of purchase, then reserve a weekly review for patterns. The first step prevents small costs from disappearing from memory. The second avoids the exhausting habit of repeatedly checking every transaction without making a decision. During that review, I would ask three questions: which category grew faster than expected, which expense was genuinely useful, and what should change before the next week begins?
This approach is especially helpful for someone paid on a regular schedule. At the beginning of a pay period, set a spending limit that feels achievable rather than optimistic. During the period, use the tracker as a warning system instead of waiting until the balance feels uncomfortable. Near the end, look for recurring behavior rather than blaming yourself for one unusual purchase. Cashew is more valuable when it supports that kind of calm reflection.
There is also a useful trade-off between speed and detail. If entering an expense takes too long, I am less likely to do it consistently. If I record only a bare amount, I may later forget why it mattered. I would therefore use a short label or a clear category for purchases that could otherwise be confusing, while keeping routine entries quick. The goal is not to create perfect records; it is to create records good enough to guide the next decision.
Using the app across different abilities and everyday situations
I find it helpful to judge Cashew not only by how quickly I can enter an expense, but by whether the routine remains comfortable across different bodies, attention styles, and daily settings. A short trial on your own device can reveal practical barriers that a feature list cannot, such as whether small controls are manageable or a quiet review works better than frequent entries. That makes accessibility part of choosing a budget habit that can last.
Motor considerations and the effort of repeated entry
Expense tracking is a repeated task, so physical effort matters even when each individual entry is small. A person with limited dexterity, hand fatigue, tremors, or difficulty with precise tapping may find frequent manual input demanding. I would not assume that a finance app is effortless simply because its purpose is simple. The real test is whether the user can complete the same action comfortably after a busy day, not whether it works once during setup.
One way to reduce strain is to batch a few entries at a calm moment instead of opening the app after every single purchase. That sacrifices some immediacy, so I would note purchases in a simple temporary way and transfer them before the list becomes difficult to remember. This is a practical compromise for users who find repeated phone interaction tiring. It also helps people who are moving between shops, commuting, or caring for someone else and cannot stop to enter every expense straight away.
At the same time, batching introduces a risk: details blur together. I would keep the temporary note short but specific, such as the amount, place, and basic category. That makes the later Cashew entry faster without turning the process into another full administrative task. If manual entry itself is a major barrier, a bank-connected or automatically importing alternative may be a better fit, even if it offers a busier interface.
Users who rely on a larger display, device magnification, or system-level text adjustments should judge the app by the smallest important controls, not by the opening screen alone. I would test the full path from creating an expense to reviewing the budget, because a screen can look clear at first and become difficult when forms, labels, or summary information appear. The app’s Everyone rating describes its intended age suitability, not a guarantee that every interaction will suit every ability.
Sensory load, visual focus, and alternative ways of paying attention
For people sensitive to visual clutter, a dedicated expense tracker can be easier to tolerate than a general-purpose money app that combines banking, promotions, investments, and alerts. Cashew’s central task is narrow, which gives the user a better chance of focusing on one decision at a time. I found that useful when I wanted to check spending without being pulled into unrelated financial information.
Still, visual simplicity and visual accessibility are not identical. A person with low vision, color-vision differences, or difficulty distinguishing subtle changes should verify that important budget information remains understandable without relying on color alone. I would also recommend using the phone’s own display settings if they make reading more comfortable, then checking whether the app remains usable after those adjustments. That is a sensible test for any finance tool because a missed digit can lead to a real budgeting mistake.
People with attention differences may appreciate the app’s single-purpose nature, but they may also struggle with the repeated need to remember entries. I would pair Cashew with a consistent cue: recording spending after arriving home, after lunch, or during a short evening routine. A cue turns an abstract intention into a concrete action. For someone with memory difficulties, the app should be treated as part of a wider reminder system rather than the only safeguard against missed expenses.
Users who prefer less visual interaction may want to experiment with their phone’s built-in voice input for entering text, if it works comfortably with their device. I would still review every amount manually before saving, since speech recognition can misunderstand digits or category names. That extra check is particularly important in a budgeting app: convenience is helpful, but accuracy has to win when the two conflict.
Situational access: when the environment changes the experience
Cashew makes the most sense in ordinary moments when I have enough attention to record a purchase. In a noisy store, while walking, during a crowded commute, or while managing children, even a short form can feel like too much. I would not force myself to use it immediately in those situations. A quick note followed by a later update is safer than entering the wrong amount while distracted.
A realistic example is a workday with several small purchases: a morning drink, lunch, a transit fare, and an unexpected household item on the way home. None of these costs feels dramatic individually, but together they can distort a weekly budget. I would jot down the details during the day, then enter them into Cashew during a quiet break or in the evening. The weekly view would then help me see whether the issue was lunch, convenience spending, or simply an unusual day.
The same approach works for shared households, but with limits. If several people spend from one household budget, Cashew can help one person maintain a record, yet the system depends on everyone communicating purchases consistently. I would agree on a simple rule before using it together: decide who records shared expenses, how reimbursements are labeled, and when the budget is reviewed. Without that agreement, the app may show a neat-looking picture that does not represent the household accurately.
Travel is another situation where the app can be useful but demanding. Different currencies, unfamiliar categories, and irregular spending make quick records valuable, but they also increase the chance of confusion. I would record the original amount and add a note that identifies the context, then review everything after returning. For a trip requiring formal reimbursement or precise exchange-rate accounting, a specialized travel-expense tool may be more suitable than a personal tracker.
Where the experience still has barriers
The biggest barrier is not necessarily the interface; it is consistency. Cashew cannot produce a trustworthy spending picture from incomplete entries. Someone who wants automatic collection from financial accounts may prefer a banking app or an expense service that imports transactions. That alternative can reduce manual work, although it may introduce more setup, more notifications, and a less focused experience.
Another limitation is the gap between personal budgeting and advanced financial management. I would choose Cashew for everyday awareness, a spending ceiling, and a simple review habit. I would look elsewhere for complex household accounting, business expenses, formal reimbursement records, investment tracking, or detailed tax preparation. Using a lightweight tool for a complicated financial job can create false confidence, which is worse than admitting that the workflow needs something more specialized.
The free price makes experimentation easy, but in-app purchases range from $1.49 to $19.99 per item. I would explore the free experience first and decide whether any paid option solves a problem I actually have. A purchase should make the routine more useful, not simply add another financial commitment to an app intended to help control spending. This is a small point, but it matters for users working with a strict budget.
People who need support across multiple devices or who share financial information with a partner should think carefully about their workflow before relying on the app. I would test how naturally it fits into the devices and habits already used at home. If a partner cannot easily see or contribute to the same record, a shared spreadsheet or household finance service may be more practical, even if it feels less polished.
I also would not mistake the strong public response for a personal guarantee. The app’s rating is encouraging, and its audience size shows that many people find value in it, but finance habits are highly individual. Someone who loves automation may dislike manual tracking. Someone who wants a calm, focused record may dislike an app that constantly connects to accounts. The right choice depends on which kind of friction you are willing to accept.
Who should use it, and who should choose another approach?
I would recommend Cashew to a student learning where monthly money goes, a first-time budgeter who finds spreadsheets intimidating, or anyone whose main problem is small daily spending that quietly accumulates. It is also a good candidate for people who want to build awareness without handing their entire financial life to a complex dashboard. The app’s free entry point makes it reasonable to test during a normal week rather than deciding based on a theoretical plan.
I would be more cautious for users who rarely remember to record transactions, who need automatic bank synchronization, or who manage finances jointly with several people. Those users may spend more energy maintaining the tracker than benefiting from it. Likewise, someone with professional accounting needs should not treat a personal expense app as a replacement for a purpose-built system.
Before making it part of my routine, I would run a short personal trial. I would record every discretionary purchase, review the totals at the end of the week, and check whether the categories actually helped me make a decision. If I kept forgetting entries, I would change the reminder routine or consider automation elsewhere. If the process felt quick and the review changed my behavior, that would be a stronger reason to continue than any rating.
It is also worth checking the technical starting point before installing: Cashew supports Android 7.0 and later. That makes it approachable for people using older compatible Android devices, but anyone on another platform or with a device outside that requirement should confirm compatibility through the relevant app store before planning around it. The app is free, though optional purchases may affect which experience a user ultimately chooses.
My inclusive verdict after looking beyond the basic budget task
Cashew—Expense Budget Tracker succeeds because it keeps the central question understandable: where is my money going, and is my current spending still within the limit I chose? I like that it can support a small, repeatable habit instead of demanding a full financial overhaul. Its focused character may also reduce cognitive clutter for people who find broad finance tools exhausting.
Its inclusive value has boundaries. Manual entry can be tiring for some users, difficult in distracting environments, and unreliable when memory or attention is already stretched. Visual comfort will depend on the individual device and settings, and people needing automation, collaboration, or professional records may be better served elsewhere. Those are not reasons to dismiss the app; they are reasons to match it to the right person and routine.
My final advice is to use Cashew as a decision aid, not as a judgment machine. Record enough detail to recognize patterns, choose a review moment that fits your life, and adjust the method when physical, sensory, or situational barriers appear. The most useful feature is the habit you can sustain without unnecessary strain. For personal expense awareness, I think this app is worth trying, especially if you want a calmer alternative to a crowded finance dashboard. If your needs begin with automation, shared access, or formal accounting, I would skip it in favor of a tool designed around those priorities.
FAQs for Cashew—Expense Budget Tracker
01What is Cashew—Expense Budget Tracker used for?
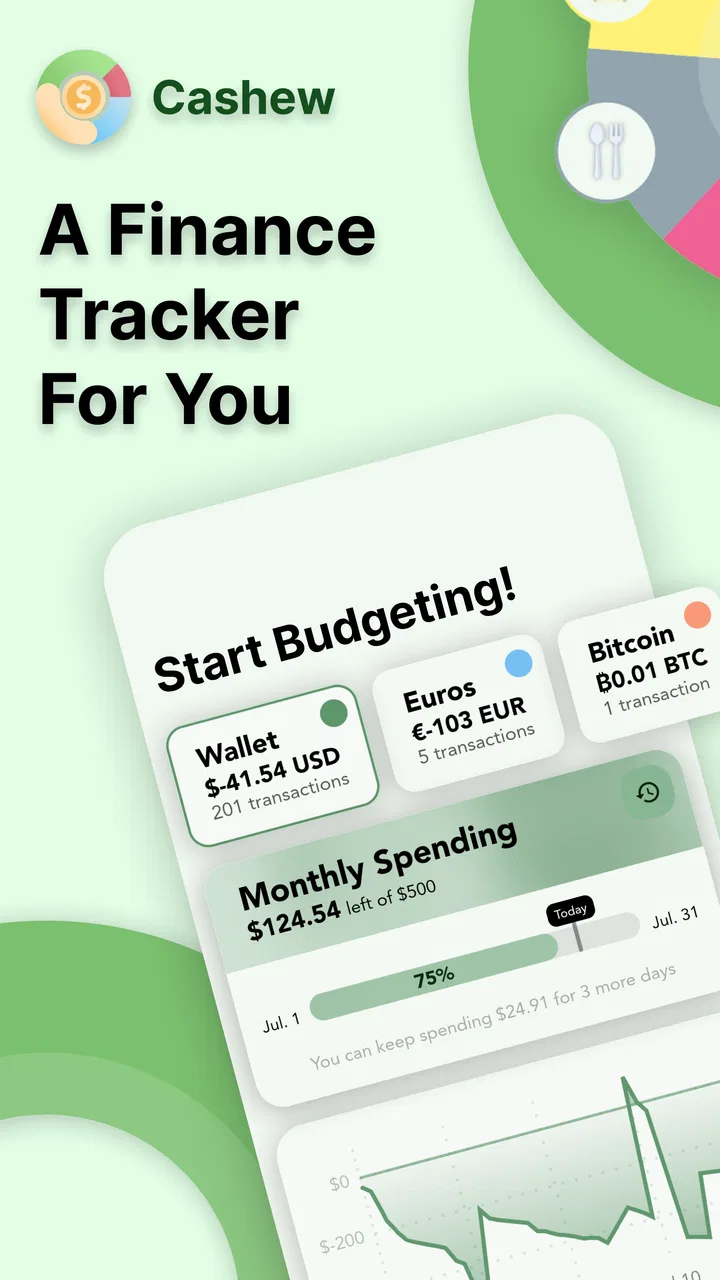
Cashew—Expense Budget Tracker is designed to help you organize personal finances in one place. You can record income and expenses, assign transactions to categories, monitor account balances, and review spending patterns over time. It is useful for people who want a clearer picture of where their money goes and prefer tracking their budget from a mobile device.
02Can I create budgets and track spending by category in Cashew?
Yes. Cashew lets you set budgets for different spending categories, such as groceries, transportation, bills, entertainment, or shopping. As you add transactions, the app helps you compare your actual spending with your planned limits. This makes it easier to identify categories where you are overspending and adjust your habits before the end of the budgeting period.
03Does Cashew support recurring transactions and scheduled payments?
Cashew includes tools for managing recurring financial activity, which can be helpful for rent, subscriptions, salary, loan payments, and other regular transactions. Setting these items up can reduce repetitive manual entry and make your budget more realistic. However, users should still review scheduled records periodically to ensure amounts, dates, and payment frequencies remain accurate.
04Is my financial information safe when using Cashew?
Before adding sensitive financial information, users should review Cashew’s current privacy policy, permissions, backup options, and any available security settings in the app store listing or within the application. Expense tracking apps may store information locally, synchronize it through a cloud service, or offer optional account features. Avoid entering banking passwords, card PINs, or unnecessary personal details.
05Does Cashew require an internet connection or offer data backup?
Cashew may allow you to manage many expense records directly on your device, but certain functions, such as synchronization, cloud backup, account access, or sharing data between devices, can depend on an internet connection and the selected settings. Before relying on the app for important records, check its export and backup tools and confirm how your information can be restored if you change or lose your device.
Pros
- Clean interface makes daily expense entry quick and easy.
- Flexible categories help organize spending across different needs.
- Budget limits provide useful warnings before overspending.
- Recurring transactions reduce the effort of tracking regular bills.
- Charts and summaries make spending patterns easier to understand.
Cons
- Some advanced features may require a premium subscription.
- Manual entry can become time-consuming for frequent transactions.
- Limited bank integration may be inconvenient for some users.
- Initial setup takes time if you have many accounts and categories.
- Backup and sync options may depend on the selected plan.

Cashew—Expense Budget Tracker
Gallery